
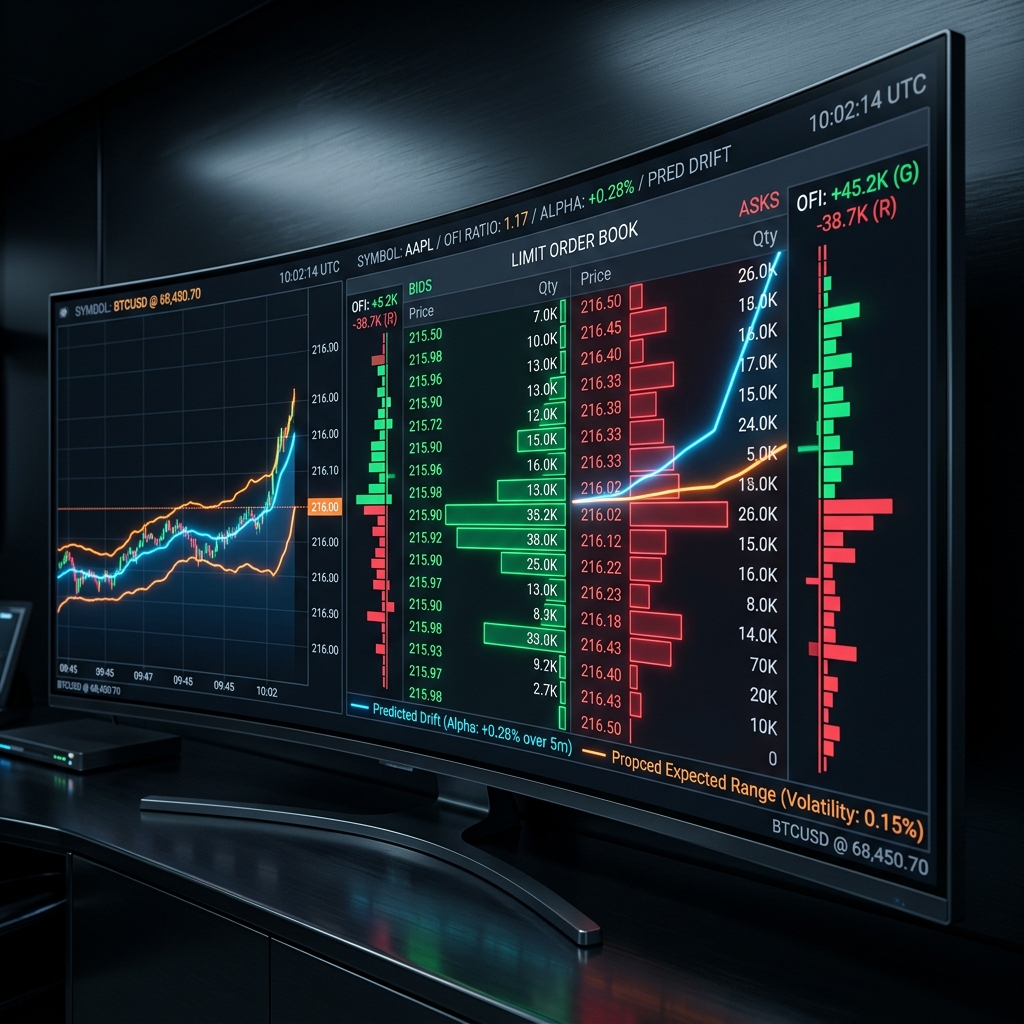
1. Introduction: Market Microstructure and Price Discovery
In high-frequency electronic markets, price discovery occurs through the continuous interaction of buy and sell orders. While standard macroeconomic models focus on daily price trends, algorithmic trading systems analyze order updates at microsecond intervals. One of the most powerful indicators of short-term price movements is **Order Flow Imbalance (OFI)**.
OFI measures the net supply and demand pressure by aggregating changes in the size and price of orders sitting at the best bid and ask levels. By capturing the direction and strength of the order flow, OFI allows quantitative models to forecast short-term price drift (alpha) before it manifests in the mid-price.
2. Mathematical Definition of Order Flow Imbalance
Let $P_t^{bid}$ and $P_t^{ask}$ be the best bid and ask prices at time $t$, and let $V_t^{bid}$ and $V_t^{ask}$ represent the quantities (volumes) available at those levels. The net demand contribution at the bid level, $\Delta I_t^{bid}$, and ask level, $\Delta I_t^{ask}$, over a time interval $\Delta t = t - (t-1)$ are defined as:
$\Delta I_t^{bid} = \begin{cases} V_t^{bid}, & \text{if } P_t^{bid} > P_{t-1}^{bid} \\ V_t^{bid} - V_{t-1}^{bid}, & \text{if } P_t^{bid} = P_{t-1}^{bid} \\ 0, & \text{if } P_t^{bid} < P_{t-1}^{bid} \end{cases}$
$\Delta I_t^{ask} = \begin{cases} 0, & \text{if } P_t^{ask} > P_{t-1}^{ask} \\ V_t^{ask} - V_{t-1}^{ask}, & \text{if } P_t^{ask} = P_{t-1}^{ask} \\ V_t^{ask}, & \text{if } P_t^{ask} < P_{t-1}^{ask} \end{cases}$
The overall **Order Flow Imbalance (OFI)** during interval $t$ is the difference between these two net contributions:
$OFI_t = \Delta I_t^{bid} - \Delta I_t^{ask}$
A positive $OFI_t$ value implies buying pressure (increasing demand or decreasing supply), which is expected to drive the mid-price upward. Conversely, a negative $OFI_t$ suggests selling pressure, predicting a downward price drift.
3. Modeling Price Drift with Linear and Non-Linear Regression
To test the predictive power of OFI, quants regress the future mid-price change $\Delta P_{t+k} = P_{t+k}^{mid} - P_t^{mid}$ over a horizon $k$ on the contemporary $OFI_t$:
$\Delta P_{t+k} = \beta \cdot OFI_t + \epsilon_{t+k}$
Empirical analyses show that this simple linear model achieves high $R^2$ values (often between 10% and 30%) on short time horizons (e.g., 10 to 100 milliseconds). To capture non-linear dynamics, such as queue depletion at outer levels of the Limit Order Book (LOB), multi-level OFI models are constructed by aggregating imbalance measurements across depth levels (L1 through L5):
| LOB Level | Description | Information Value | Predictive Impact |
|---|---|---|---|
| Level 1 (Best Bid/Ask) | Primary queue events (fills, cancellations, inserts). | Very High | Directly correlates with immediate price changes. |
| Levels 2 - 5 | Order book replenishment and depth adjustments. | Moderate | Signals trend sustainability and support/resistance strength. |
4. Python Implementation: Calculating Level 1 OFI
The following Python script implements the calculation of Order Flow Imbalance based on tick-by-tick order book updates:
import numpy as np
import pandas as pd

def calculate_ofi(lob_df):
    """
    Computes Level 1 Order Flow Imbalance (OFI) from tick-by-tick order book data.
    Expected columns in lob_df: ['bid_price', 'bid_vol', 'ask_price', 'ask_vol']
    """
    # Shift values to obtain t-1 state
    prev = lob_df.shift(1)

    # Initialize bid and ask contribution arrays
    bid_contrib = np.zeros(len(lob_df))
    ask_contrib = np.zeros(len(lob_df))

    # Bid price increases -> full current volume
    mask_bid_inc = lob_df['bid_price'] > prev['bid_price']
    bid_contrib[mask_bid_inc] = lob_df['bid_vol'][mask_bid_inc]

    # Bid price remains constant -> change in volume
    mask_bid_eq = lob_df['bid_price'] == prev['bid_price']
    bid_contrib[mask_bid_eq] = lob_df['bid_vol'][mask_bid_eq] - prev['bid_vol'][mask_bid_eq]

    # Ask price increases -> 0 contribution (selling pressure moved further up)
    # Ask price remains constant -> change in volume
    mask_ask_eq = lob_df['ask_price'] == prev['ask_price']
    ask_contrib[mask_ask_eq] = lob_df['ask_vol'][mask_ask_eq] - prev['ask_vol'][mask_ask_eq]

    # Ask price decreases -> full current volume
    mask_ask_dec = lob_df['ask_price'] < prev['ask_price']
    ask_contrib[mask_ask_dec] = lob_df['ask_vol'][mask_ask_dec]

    # OFI is the net difference
    ofi = bid_contrib - ask_contrib
    return ofi

# Example usage:
# data = pd.DataFrame({
#     'bid_price': [100.1, 100.1, 100.2],
#     'bid_vol':   [500,   600,   450],
#     'ask_price': [100.2, 100.2, 100.3],
#     'ask_vol':   [300,   250,   400]
# })
# print(calculate_ofi(data))
5. Conclusion
Order Flow Imbalance provides a highly robust signal of short-term supply and demand dynamics in electronic matching engines. Combining multi-level OFI calculations with machine learning architectures allows algorithmic execution setups to optimize order routing, capture microsecond alpha spreads, and manage execution slippage effectively.